India's IT stocks just had a week that has not happened since April 2008. Nifty IT, the NSE's index of the sector, rallied 11.72 percent in the week to October 16, 2026, its biggest weekly gain since April 2008. The easy read is that the market is pricing a recovery in demand for Indian technology services, and for two of the big names the order books agree. TCS reported total contract value of $9.6 billion for the September 2026 quarter, and HCLTech's new deal bookings reached $3.258 billion, up 27 percent from a year earlier.
It is worth slowing down on Wipro, because its numbers say something different.
The order book that shrank
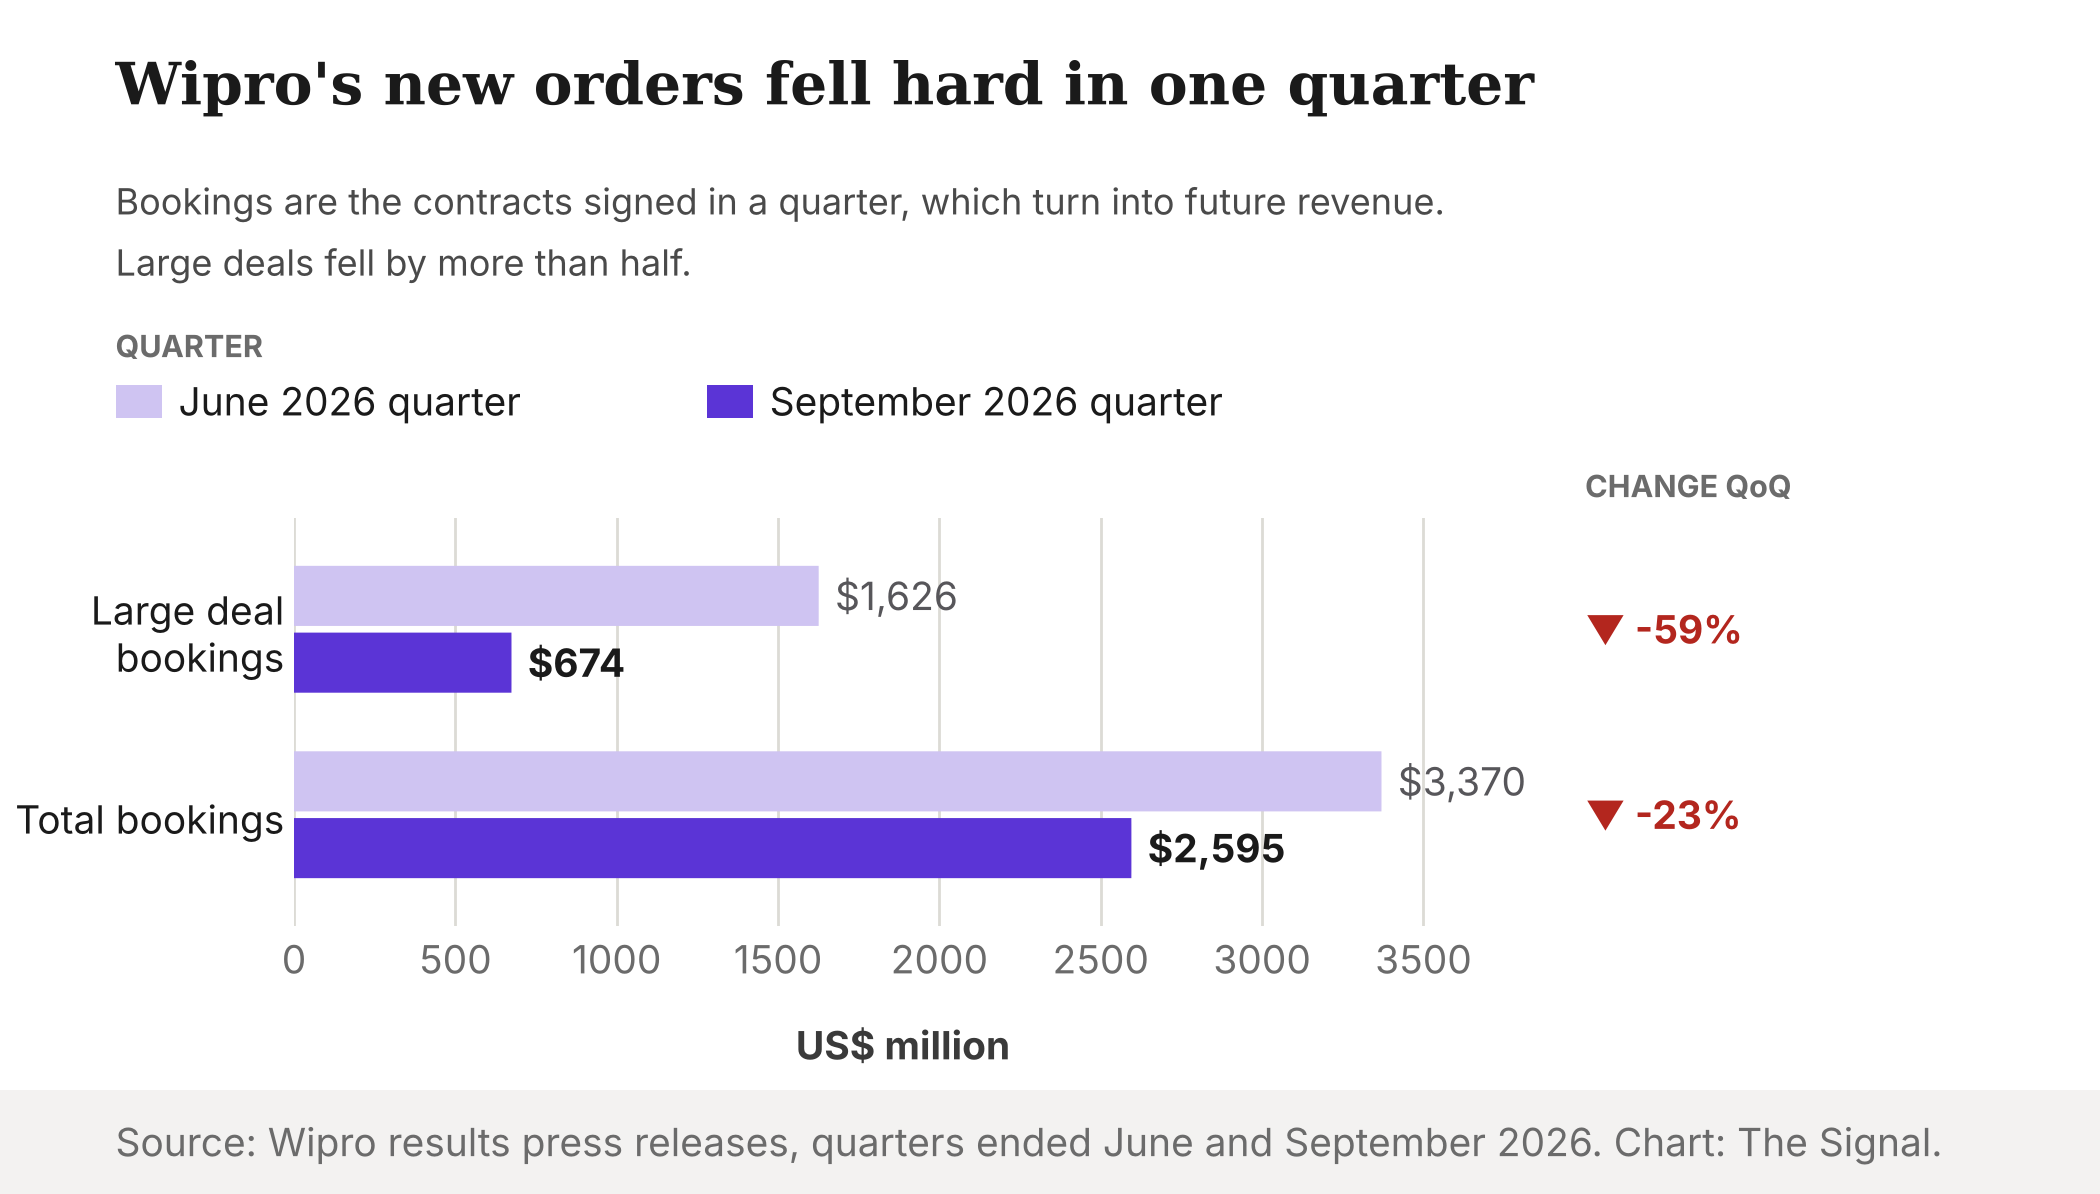
Bookings are the contracts a services firm signs in a quarter. They become revenue over the following months, so they are the closest thing the sector has to a forward indicator. Wipro's large deal bookings were $674 million in the September 2026 quarter, down 58.6 percent from the June quarter in constant currency. In the June quarter, they had been $1,626 million. Total bookings fell too: $2,595 million, down 22.9 percent, against $3,370 million in the June quarter.
The revenue side gives no cushion. Wipro's IT services revenue was $2,611.5 million, down 0.1 percent from the prior quarter and up 0.3 percent from a year earlier. Set that beside the bookings and the picture is plain: $2,595 million of new contracts against $2,611.5 million of quarterly revenue means Wipro signed about one dollar of new work for every dollar it delivered. For a firm that wants to grow, that is a standstill.
The company's own outlook says the same. Wipro guides December-quarter IT services revenue to between $2,571 million and $2,625 million, a range of minus 1.5 percent to plus 0.5 percent from the September quarter in constant currency. The midpoint is a small decline.
What the market paid for it
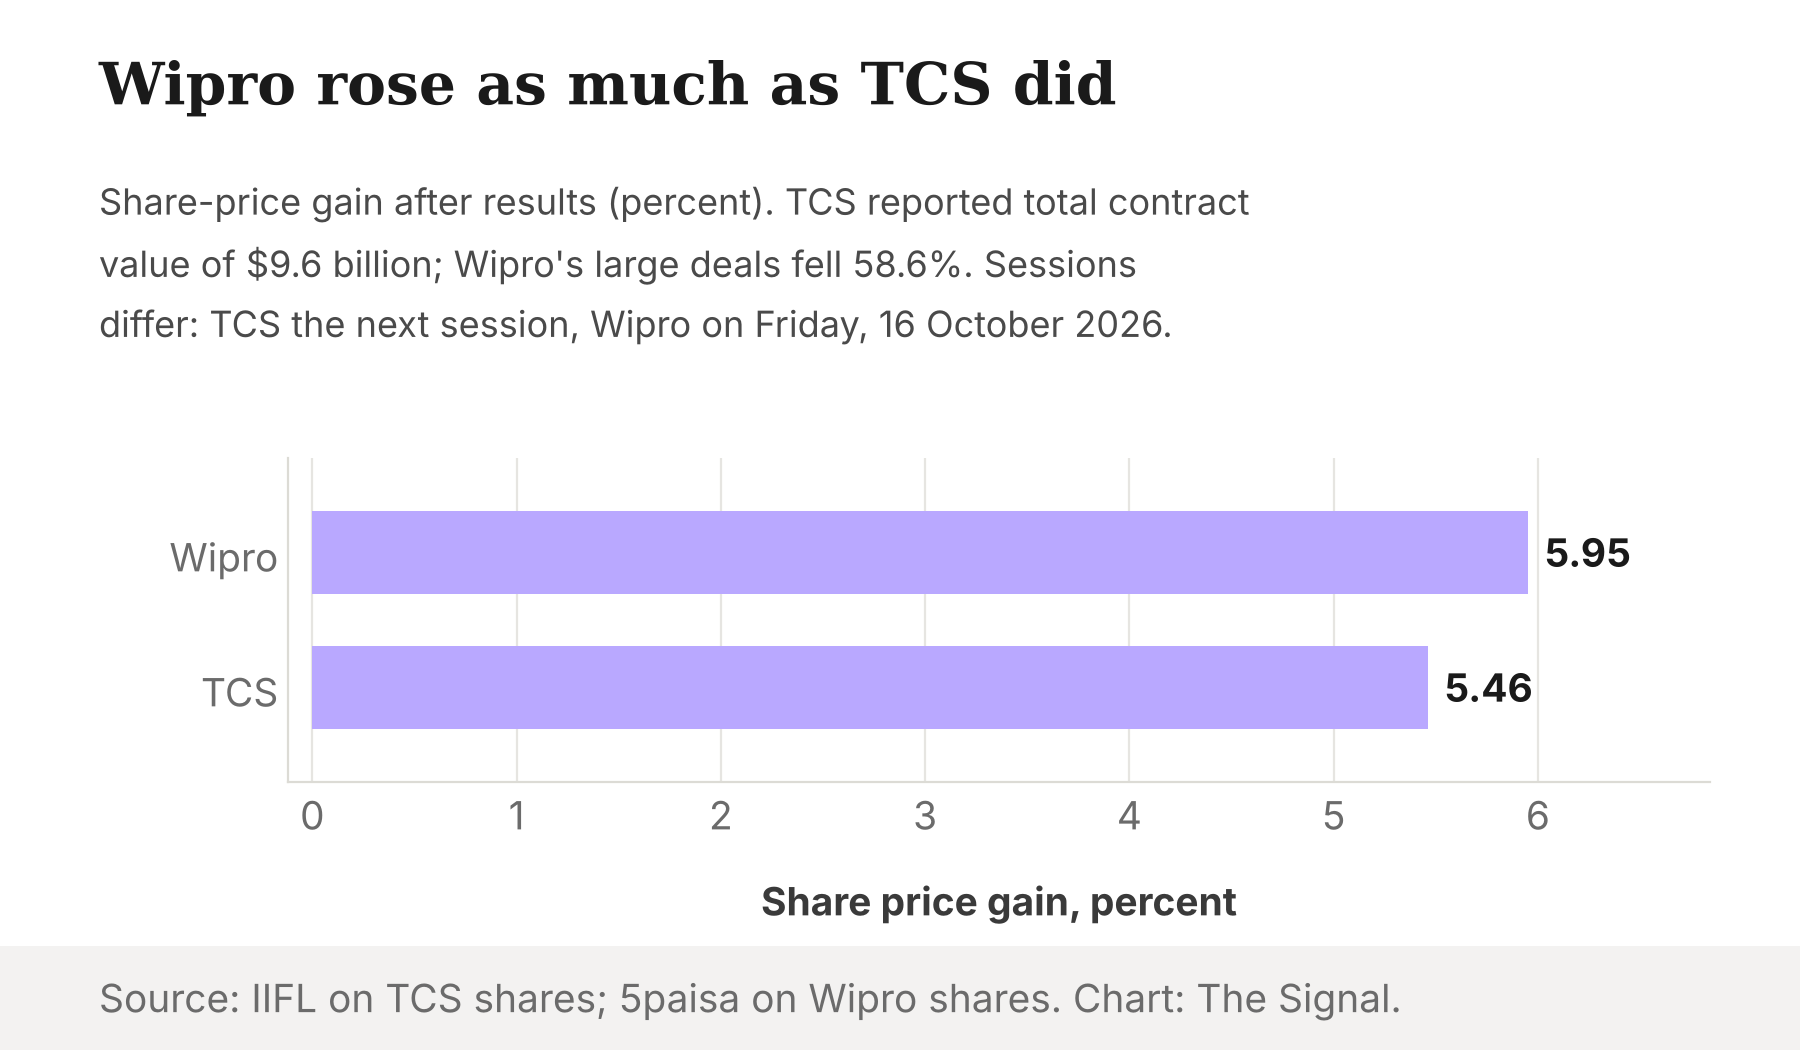
Wipro reported after the close on October 15. On Friday, Wipro gained 5.95 percent, as investors responded to its quarterly revenue performance and business outlook. TCS, whose contract value was the stronger story, rose 5.46 percent after its own results.
| Company | September 2026 quarter bookings signal | Share move after results |
|---|---|---|
| TCS | Total contract value of $9.6 billion | Up 5.46 percent |
| HCLTech | New deal bookings of $3.258 billion, up 27 percent year on year | Up more than 7 percent |
| Wipro | Large deals down 58.6 percent, total bookings down 22.9 percent | Up 5.95 percent |
Sources: IIFL for TCS, Kotak Neo for HCLTech, Wipro's release and 5paisa for Wipro. The share moves cover different sessions, so they are not a like-for-like race.
The sessions differ, and that matters: each move bundles a company's own news with the sector's mood on that day. But that is the point. If the market were sorting winners from losers by order book, Wipro would have lagged. Instead the best weekly gain in 18 years lifted the one name whose forward indicator moved the wrong way.
The honest objection
The strongest case against this reading is that large deals are lumpy. A single multi-year contract can swing a quarter by hundreds of millions of dollars, and a quarter after a $1,626 million print was always likely to look smaller. On that view, Wipro's $674 million is a normalisation, not a collapse, and investors who looked through it were being sensible.
That case has force, and it is why the claim here is narrow. Total bookings still fell 22.9 percent, and the guidance range is the company's own, not an analyst's gloss. Lumpiness explains why the large-deal line is volatile. It does not explain why the market raised Wipro's price by nearly the same amount as TCS's when the company itself guided to flat revenue. A recovery trade that rewards everything in the sector is a bet on the sector turning, which can be right. It is a different bet from one on order books.
The Signal
Nifty IT's week was built on strong prints from TCS and HCLTech, and the rally is not baseless. But it also lifted a company that signed less than half the large-deal value it signed one quarter earlier and guided to a flat December quarter. That is what a sector trade looks like: the price moves with the group before the contracts show up. The test comes over the next two quarters. If Wipro's bookings recover toward the $1,626 million of June, the market was early and right. If they do not, the guidance range of minus 1.5 percent to plus 0.5 percent is the number the 5.95 percent gain will have to answer to.
Reporting basis: Wipro's bookings, revenue and guidance figures are from Wipro's own results press releases for the quarters ended June 30 and September 30, 2026, which are the primary artifacts and were checked directly. The Nifty IT weekly gain and the Wipro share move are per 5paisa's post-market report, which relays exchange data and was not checked against NSE directly. TCS's contract value and share move are per IIFL's results report, reporting TCS's results; HCLTech's bookings and guidance are per Kotak Neo's report, reporting HCLTech's results. Neither TCS's nor HCLTech's own filings were reachable, so each rests on one outlet. The Signal's calculation is the roughly one-to-one ratio of Wipro's total bookings to its quarterly IT services revenue, drawn from the figures above.