The headline circulating this week is simple. Indians spent less on credit cards in September. Add the RBI's two September lines together, ₹77,751 crore at point-of-sale terminals and ₹1,26,074 crore online, and the total is about ₹2.04 lakh crore. A year earlier, September 2025 saw ₹72,544 crore in-store and ₹1,44,118 crore online, about ₹2.17 lakh crore. That is a fall of 5.9 percent, and it is real. With the RBI having just raised the repo rate, it is easy to read as households pulling back.
It is worth slowing down on that. A year-on-year drop has two parents: what happened in September 2026, and what happened in September 2025.
The month that moved was last year's
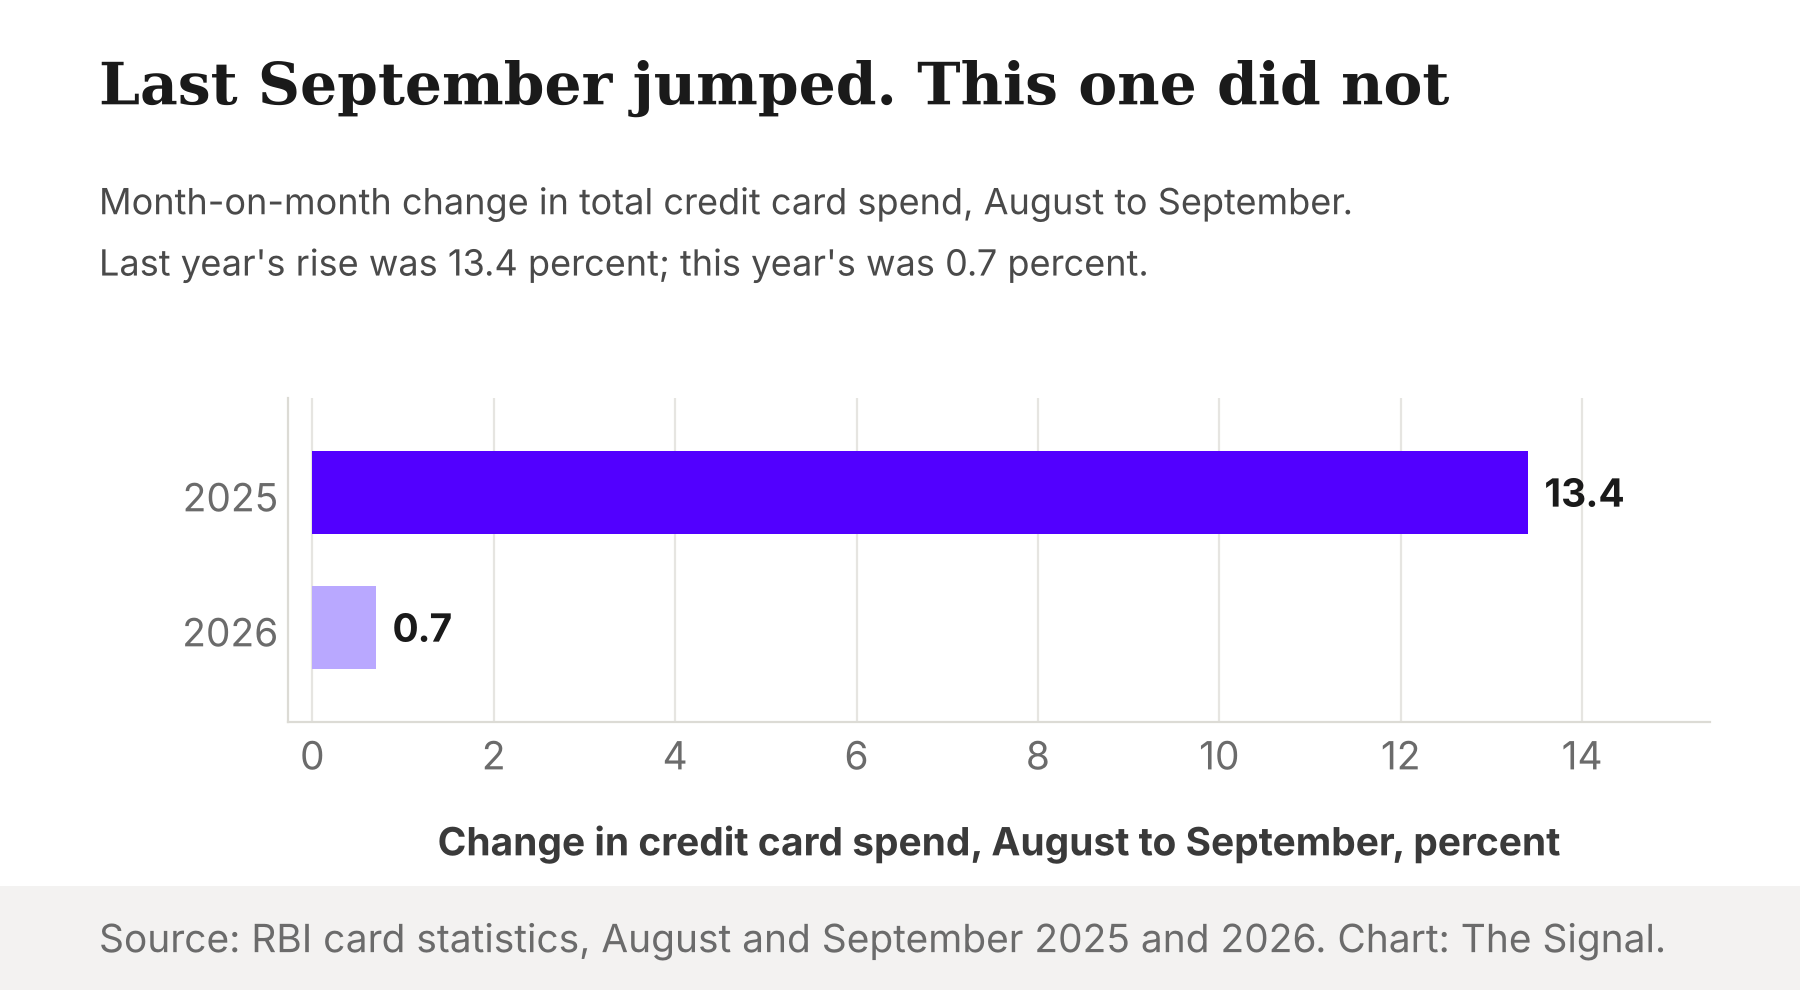
Start with this year. August 2026 card spend was ₹79,355 crore in-store and ₹1,22,980 crore online, about ₹2.02 lakh crore. September's ₹2.04 lakh crore is 0.7 percent higher than that. Nothing fell from August to September 2026. Spend edged up.
Now last year. In August 2025 the RBI recorded ₹72,753 crore in-store and ₹1,18,381 crore online, about ₹1.91 lakh crore. September 2025's ₹2.17 lakh crore was 13.4 percent above that. One September rose by a seventh from August. The other barely moved.
Last September jumped 13.4 percent on August. This September rose 0.7 percent.
The 5.9 percent fall is the gap between those two Septembers (2026 and 2025), not a slide from this August.
Spend per card sits near its 2024 level
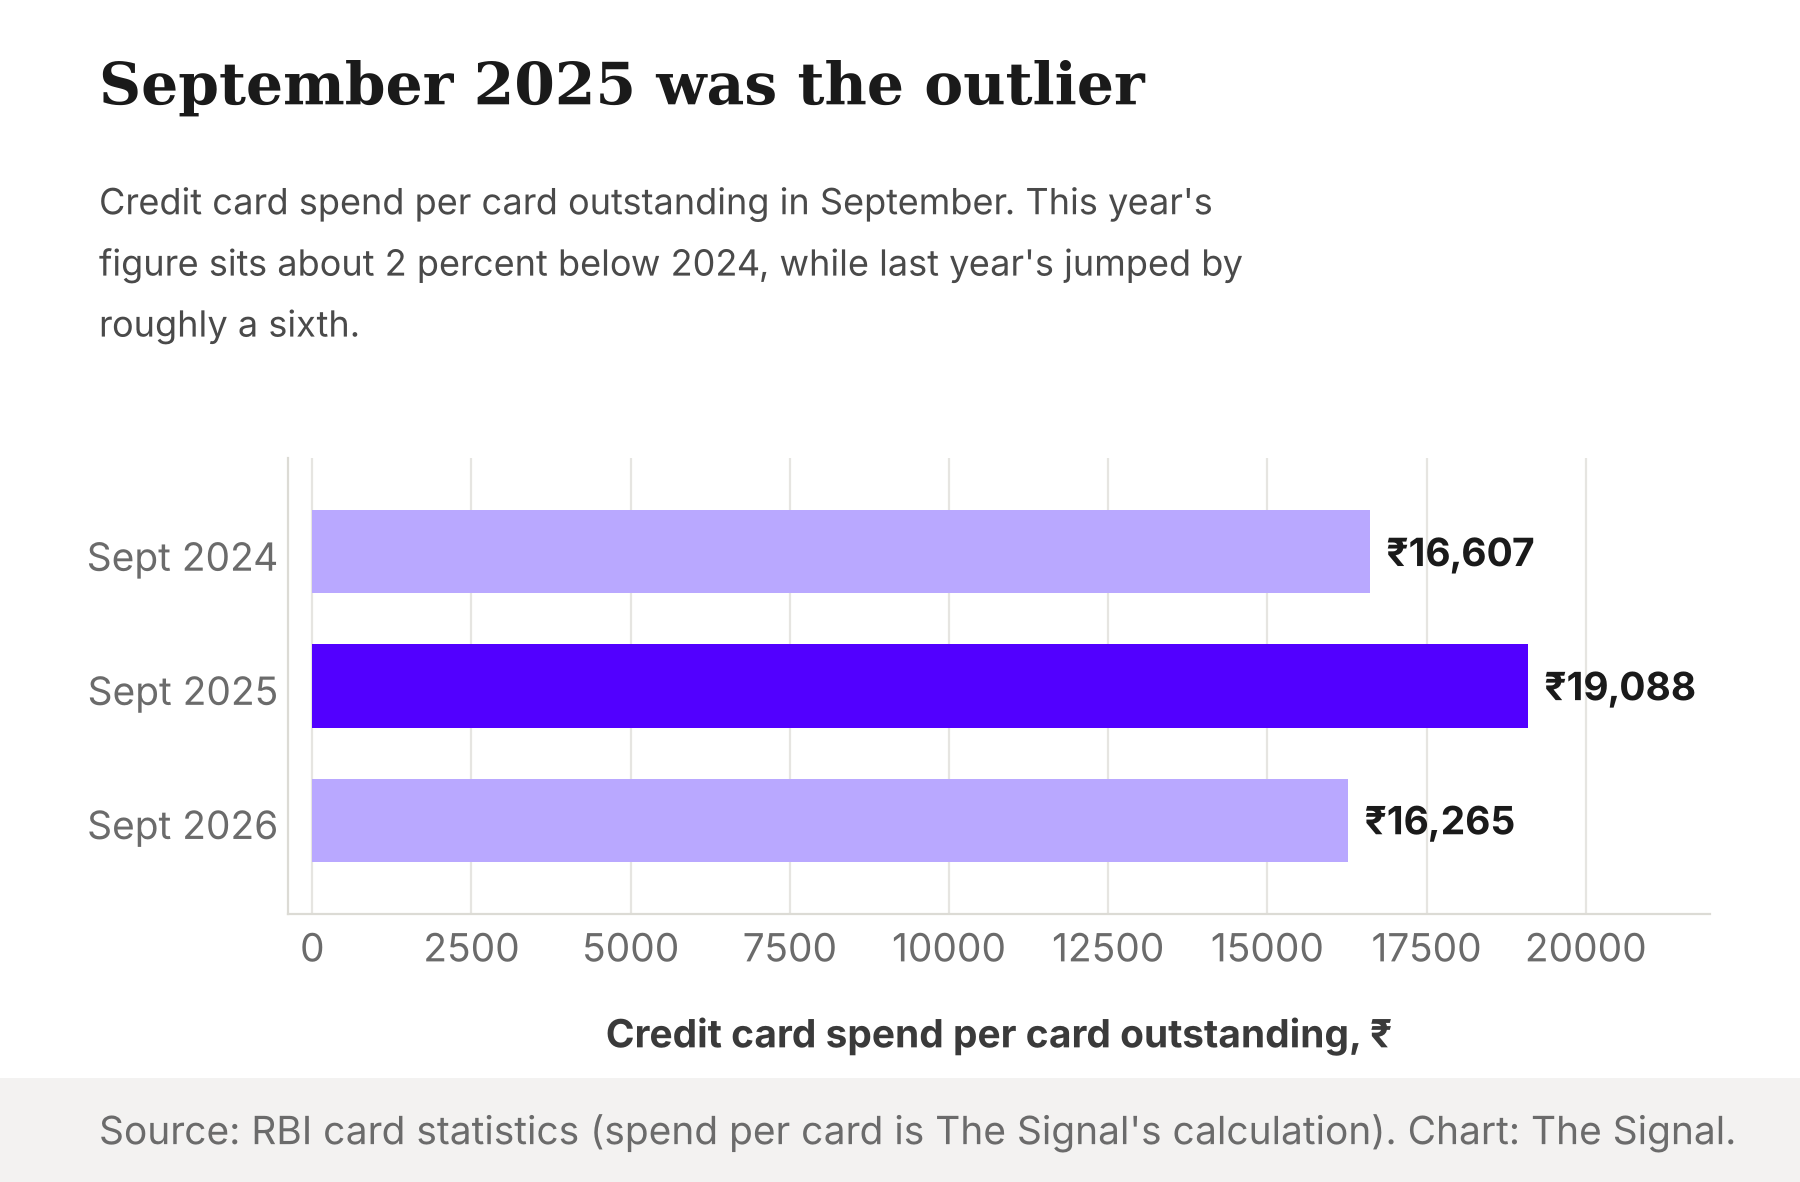
The second number is the card count. India had 125,315,381 credit cards outstanding at the end of September 2026, against 113,507,240 a year earlier. That is 10.4 percent more cards. More cards sharing less spend means each card carried less: ₹16,265 in September 2026 against ₹19,088 in September 2025, a drop of 14.8 percent (our calculation, total spend divided by cards outstanding).
That looks like a collapse in usage until you add a third September. In September 2024 credit cards had 106,103,318 in circulation and spend of ₹60,857 crore in-store and ₹1,15,345 crore online, about ₹1.76 lakh crore. Divided across those cards, that is ₹16,607 per card. This September's ₹16,265 is only 2.1 percent below it. August 2026's ₹16,317 per card is almost identical.
Spend per card was ₹16,607 in September 2024, ₹19,088 in 2025 and ₹16,265 in 2026.
Total spend in September 2026 is still 15.7 percent above September 2024. Over the same two years the card count grew by about 18 percent, from 106.1 million to 125.3 million. Spending grew, but a little slower than the number of cards. September 2025 stands out as the exception, not the new norm.
The decline is all online
The split by channel adds one more fact. In-store spend rose from ₹72,544 crore to ₹77,751 crore between September 2025 and September 2026, up 7.2 percent. Online spend fell from ₹1,44,118 crore to ₹1,26,074 crore, down 12.5 percent. Online's share of credit card spend slipped from 66.5 percent to 61.9 percent.
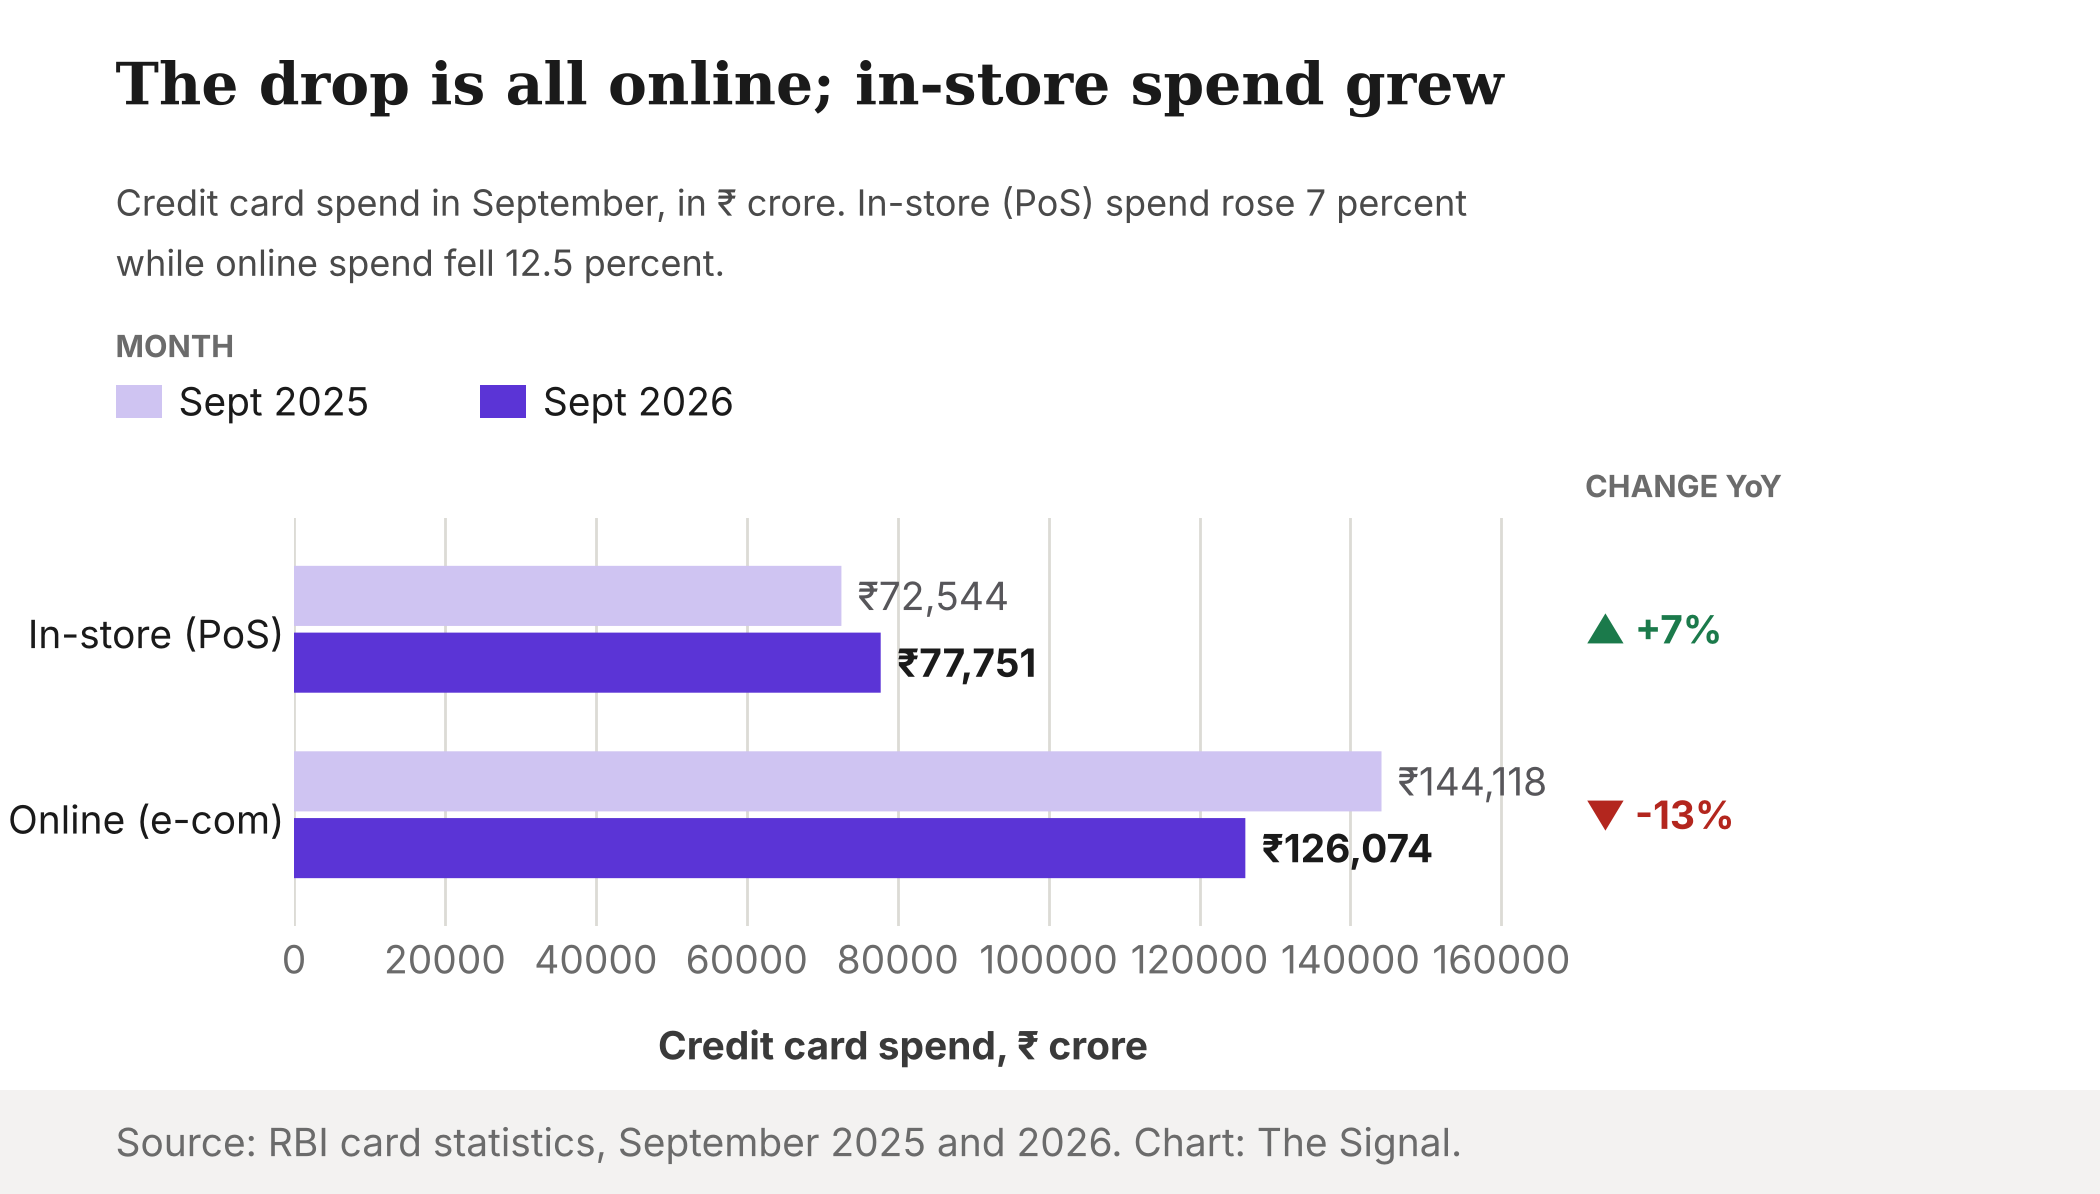
The RBI series does not say why. Timing of festive-season buying is one candidate, but that is a hypothesis, not a finding, and these tables cannot test it. What they do show is that the drop sits in one channel, which is not how a broad household pullback looks.
The honest objection
The strongest case against this reading is that a base effect explains the size of the fall, not its existence. Spending per card did drop from last year. The RBI's August 2026 credit release said credit card outstanding balances decelerated, even as personal loans grew 16.9 percent and non-food bank credit grew 18.8 percent. And on October 7, the Monetary Policy Committee raised the repo rate by 25 basis points to 5.50 percent. Slower card balances ahead of a rate rise could be early caution.
That case is plausible, and September's data cannot rule it out. But it does not fit the figures well. Spend rose from August, the card base grew by 10 percent, and in-store spend grew while online fell. A cautious household usually trims everywhere. Caution would also show up as slower balances and a lower per-card level than two years ago, and per-card spend is within about 2 percent of September 2024.
The Signal
The 5.9 percent figure is accurate and misleading in the same sentence. It compares September 2026 with an unusually strong September 2025, when spend rose 13.4 percent on August 2025. Against September 2024, spend is up 15.7 percent, and per-card spend is about level.
The test comes in the next RBI card releases for October and November, which follow the October 7 repo-rate rise. If per-card spend there falls below this September's ₹16,265, the caution reading gains ground. If it climbs, September was a timing gap and nothing more. A headline that compares one month with its year-ago twin tells you which month was odd. It does not tell you which year was normal.
Reporting basis: every card figure comes from a single origin, the Reserve Bank of India's monthly ATM, Acceptance Infrastructure and Card Statistics, which are marked provisional and for some months revised; September 2026 is provisional. The credit growth and deceleration findings are from the RBI's Sectoral Deployment of Bank Credit release for August 2026, and the repo rate decision is from the Governor's statement of October 7, 2026. Because the piece rests on one compiler, a revision to the RBI tables would change the figures here. Totals (in-store plus online), month-on-month and year-on-year changes, per-card spend, channel shares and the card-growth comparison are The Signal's calculations from those figures.